Pet Insurance Annual Limits Explained
A pet insurance annual limit is the maximum your insurer will pay out in reimbursements during one policy year — once claims reach that cap, every additional vet bill is yours until the policy renews and the limit resets. Common options run from $2,500 up to unlimited, and the limit works after your deductible and reimbursement percentage, which is where most of the confusion (and most of the unpleasant surprises) live. This guide walks through the four cap structures, the order of operations, and a fully worked example. Since the right limit depends on what a bad year could actually cost you, start by checking your dog's normal-year baseline with the free dog cost calculator.
What Is a Pet Insurance Annual Limit?
The annual limit (also called the annual maximum, payout cap, or coverage limit) is the total amount of reimbursement your insurer will pay across all claims in one policy year. If your plan has a $5,000 annual limit and your reimbursements hit $5,000 in March, the policy is effectively dormant until your renewal date — you still pay premiums, but every bill from April to renewal is fully out of pocket.
Three details define how it behaves:
- It caps payouts, not vet bills. Because your deductible and co-share come off first, a $5,000 limit actually survives more than $5,000 of vet bills — the worked example below shows exactly how much more.
- It resets at renewal. Each new policy year starts the count at zero, which is what makes annual limits workable for chronic conditions that bill every year.
- It's chosen at signup and adjustable at renewal. Along with your deductible and reimbursement percentage, it's one of the three levers that set your premium — the full lever-by-lever breakdown is in what affects your premium.
If you're still getting oriented on how claims and reimbursement flow overall, skim how pet insurance works first — this guide zooms in on just the cap.
Annual vs Per-Incident vs Lifetime vs Unlimited: What's the Difference?
Not every policy caps payouts the same way, and the structure matters as much as the number. Here are the four you'll encounter:
| Limit type | How it works | Resets? | The catch |
|---|---|---|---|
| Annual | One pool (e.g., $5,000–$15,000) covering all claims per policy year | Yes, every renewal | A single catastrophic year can exhaust it |
| Per-incident | A separate cap (e.g., $3,000) for each distinct condition or injury | Varies — often no reset for the same ongoing condition | One expensive condition maxes out even if total spending is modest |
| Lifetime | One total cap for the dog's entire life (e.g., $25,000) | Never | Chronic illness can quietly consume it years before old age |
| Unlimited | No ceiling on payouts | Nothing to reset | Higher premium; deductible and co-share still apply to every claim |
A few practical notes on each:
Annual limits dominate the US market and are the most predictable: one number, one pool, fresh every year. For most dogs, a well-chosen annual limit behaves almost identically to unlimited coverage — the difference only appears in genuinely catastrophic years.
Per-incident caps deserve careful reading. If cruciate ligament surgery on one knee runs $5,500 and your per-incident cap is $3,000, the excess is yours even though your other coverage sits untouched. Worse, some policies treat an ongoing condition as a single "incident" forever — so a chronic illness that exhausts its incident cap in year one may never be paid on again. If a policy quotes both a per-incident and an annual number, the smaller one is the one that will bite.
Lifetime caps are less common in the US than they once were, but they still appear, sometimes stacked on top of annual limits. A $25,000 lifetime cap sounds enormous until you price a chronic condition at $3,000 a year from age four onward.
Unlimited plans remove ceiling risk entirely. They are not "everything free" — your deductible and reimbursement share apply to every claim, and exclusions still exclude (see what pet insurance covers for those boundaries). What you're buying is the guarantee that no single terrible year can out-spend the policy.
How Does the Annual Limit Work With Your Deductible and Reimbursement?
This is the mechanic most owners get wrong, so here's the order of operations on every claim:
- Exclusions first. Only covered costs enter the math at all.
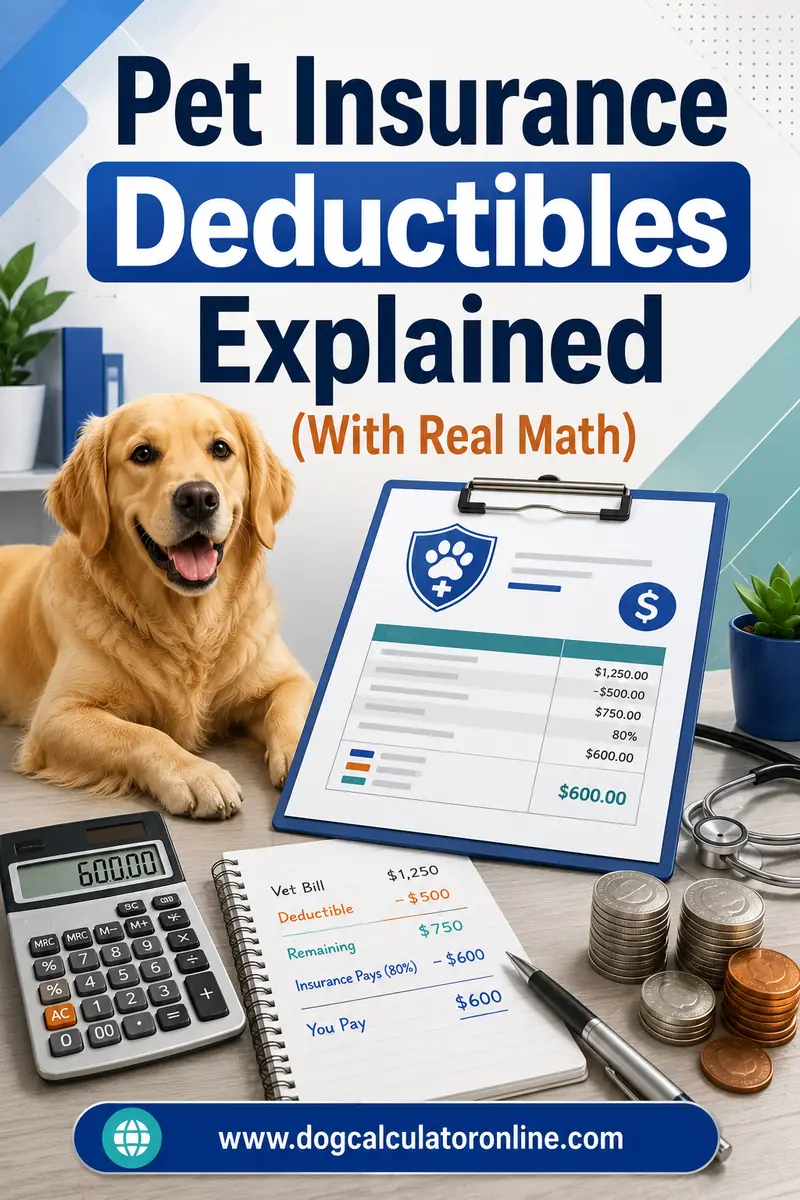
- Deductible next. Your annual deductible comes off the covered amount — details in the deductible guide.
- Reimbursement percentage. The insurer pays its share (70/80/90%) of what remains — see the reimbursement guide for that layer.
- Annual limit last. The insurer pays its calculated share until total payouts for the year reach the cap, then stops.
Because the cap applies to the insurer's payout — the final number, after steps 2 and 3 shrink it — your limit stretches further across gross vet bills than its face value suggests. On an 80% plan with a $500 deductible, a $5,000 annual limit isn't exhausted until roughly $6,750 of covered bills in a year. That's the good news. The bad news is symmetrical: in a truly catastrophic year, the cap binds exactly when you're least able to absorb the overflow.
A Fully Worked Example
Meet a hypothetical Lab mix with a rough year, on a common plan: $500 annual deductible, 80% reimbursement, $5,000 annual limit.
Claim 1 — February. Swallowed a corn cob: $3,500 surgery (covered).
- Covered bill: $3,500 → minus $500 deductible = $3,000
- Insurer pays 80% of $3,000 = $2,400 · You pay $1,100
- Annual limit used: $2,400 of $5,000 → $2,600 remaining
Claim 2 — June. Cruciate ligament tear: $4,500 surgery (covered).
- Deductible already met this year, so: 80% of $4,500 = $3,600 calculated
- But only $2,600 remains under the cap → insurer pays $2,600
- You pay $1,900 (your 20% share of $900, plus the entire $1,000 overflow)
- Annual limit used: $5,000 of $5,000 → $0 remaining
Claim 3 — October. Ear infection: $300 (covered).
- Limit exhausted → insurer pays $0. You pay all $300.
Year totals: $8,300 in vet bills; insurer paid $5,000; the owner paid $3,300. On renewal day, the limit resets to $5,000, the deductible resets too, and the count starts over.
Run the same year on a $10,000 limit and the insurer pays $6,240 ($2,400 + $3,600 + $240, since the June claim is no longer capped and the ear infection reimburses normally), leaving the owner about $2,060. Run it on a $2,500 limit and the owner absorbs about $5,800. Same dog, same bills — the cap choice alone moved thousands of dollars from one column to the other. That's the decision you're making at signup, and it's why cap-shopping purely to shave the premium is the classic false economy.
What Happens When You Hit Your Annual Limit?
Mechanically, it's simple and unforgiving:
- Reimbursements stop immediately. Claims submitted after the cap is reached are processed at $0, even for conditions the policy was happily paying on last month.
- Premiums continue. The policy is still in force — you're paying to keep it (and your dog's insurability) alive until the reset.
- The reset arrives at renewal, not January 1st. A policy started in August resets every August.
- You usually can't raise the limit mid-year. Cap increases typically take effect at renewal, and treatment already underway may be assessed under the old terms. If you suspect a big year coming, the time to upsize the limit is the renewal before it.
This is also the moment the insurance-versus-savings question stops being either/or. Owners with a modest cap and a modest emergency fund are far more resilient than owners with either alone — the fund's whole job becomes covering deductible, co-share, and any overflow above the cap.
How Much Annual Limit Does a Dog Actually Need?
There's no universal number, but the honest way to choose is to price the bad year, not the average year. Ballpark anchors from US veterinary pricing:
- A serious emergency (foreign-body surgery, hit-by-car, bloat) commonly runs $3,000–$8,000 all-in.
- Cruciate ligament surgery: $3,000–$6,000 per knee — and the second knee follows the first in a large share of dogs.
- Cancer diagnosis and treatment with a specialist: $5,000–$15,000+ across a year.
- A bad year is often two problems, not one — emergencies don't queue politely.
Against those anchors, rough guidance:
- $5,000 covers most single emergencies for most dogs, with the worked-example caveat that one big surgery plus anything else can breach it. A reasonable floor for small, low-risk mixed breeds.
- $10,000 absorbs a major surgery plus a second problem, or a serious diagnosis year, for the large majority of dogs. The sweet spot for most owners balancing premium against protection.
- Unlimited (or $15,000+) earns its premium for large and giant breeds, orthopedic- and cancer-prone breeds, and any owner whose plan B for a $12,000 estimate is "there is no plan B."
Whatever you choose, revisit it at renewal as your dog ages — senior-dog bad years are more expensive and more likely than puppy ones.
It also helps to sanity-check the cap against your own finances rather than the dog's risk alone. The question isn't "will my dog ever have a $12,000 year?" — nobody knows that. The question is "if the overflow above my cap landed on my card tomorrow, could I pay it without real damage?" An owner who could absorb a $5,000 overflow can rationally run a lower cap and pocket the premium difference for years. An owner who couldn't cover $2,000 on short notice is exactly who higher caps exist for, because the cap is the line where the insurer's problem becomes yours again.
Is an Unlimited Plan Worth the Extra Premium?
Sometimes — and the framing that helps is to ask what the extra premium buys. Moving from a $5,000 or $10,000 cap to unlimited typically adds a modest monthly amount (varies widely by dog and region). What it buys is protection against exactly one scenario: the year where covered bills blow past your cap. For a young, small, mixed-breed dog, that year is uncommon, and a $10,000 cap plus the savings in premium may serve you better. For a Golden Retriever (a breed with well-documented cancer rates), a giant breed, or any dog whose worst case you couldn't self-fund, unlimited is cheap certainty.
One warning either way: an unlimited limit doesn't mean unlimited coverage. Exclusions, the deductible, and your co-share apply in full — an unlimited plan with 70% reimbursement still leaves you holding 30% of a $15,000 year, which is $4,500. The cap is one wall of the box, not the whole box.
What Should You Check in the Fine Print?
Five limit-related questions to answer before you enroll — the answers are all in the sample policy, which insurers publish:
- Is the limit annual, per-incident, lifetime, or some stack of them? If two numbers appear, the smaller one governs your worst case.
- Does an ongoing condition's per-incident cap ever reset? "Per condition, per lifetime" is a very different product from "per condition, per year."
- Are there hidden sub-limits? Some policies cap specific categories — exam fees, dental, alternative therapy — inside the big limit.
- When exactly does the reset happen, and does a claim spanning the renewal date count against the old year or the new one?
- Can you change the limit at renewal, and does raising it trigger new waiting periods or reviews? Practices vary; know before you need it.
Ten minutes with the sample policy answers all five and tells you more than any marketing page will.
Frequently Asked Questions
What does annual limit mean in pet insurance?
It's the maximum total your insurer will reimburse across all claims in one policy year. After payouts reach the cap, further bills are fully out of pocket until the policy renews, when the limit resets to its full amount.
Is a $5,000 annual limit enough for a dog?
For many small, low-risk dogs, usually — it covers most single emergencies. But one major surgery plus a second problem can breach it, as can cancer treatment. Large breeds, orthopedic-prone breeds, and owners without backup savings are generally better served by $10,000 or more.
Does the annual limit apply before or after the deductible?
After. Covered bills are reduced by your deductible, multiplied by your reimbursement percentage, and only that final payout counts against the limit. That means a $5,000 limit actually stretches across roughly $6,750 of covered bills on a typical $500-deductible, 80% plan.
What's the difference between an annual limit and a per-incident limit?
An annual limit is one pool covering everything, refreshed each year. A per-incident limit caps each separate condition — and in some policies an ongoing condition's cap never resets, so a chronic illness can permanently max out while the rest of the policy still functions. Policies can carry both; the smaller number bites first.
Do unlimited pet insurance plans really have no cap?
They have no payout ceiling, yes — but the deductible, reimbursement percentage, and all policy exclusions still apply. You'll still pay your share of every bill; what unlimited removes is the scenario where the insurer stops paying mid-year.
Does my annual limit reset if I switch insurers?
A new policy starts a fresh limit, but switching has a serious cost: everything in your dog's medical history becomes pre-existing to the new insurer and won't be covered. Raising the limit with your current insurer at renewal is almost always safer than switching for a bigger cap.
The Bottom Line
The annual limit is the ceiling on what your policy can do for you in its worst — and therefore most important — year. Know which structure you're buying (annual, per-incident, lifetime, unlimited), remember it caps payouts after the deductible and percentage do their work, and size it against a realistic bad year for your dog's breed and size rather than an average one. Then check the whole budget picture — premium, food, routine care, and an emergency cushion for your share of the bills — with the free dog cost calculator.