What Is a Pet Insurance Waiting Period? (And How to Beat It)
A pet insurance waiting period is the stretch of time between when your policy starts and when coverage actually begins — typically 2 to 14 days for accidents, around 14 days for illnesses, and up to 6 months for orthopedic conditions like cruciate ligament tears. Anything that shows symptoms during the wait counts as pre-existing and stays excluded, which makes this small print surprisingly important. This guide explains how waiting periods work, why they exist, and the legitimate ways to shorten them — no carrier pitches. For the budget side of the decision, the free dog cost calculator shows where a premium fits in your dog's total costs.
The Typical Waiting Periods, By Claim Type
| Claim type | Typical waiting period | Range across insurers |
|---|---|---|
| Accidents & injuries | ~14 days | 1–15 days |
| Illnesses | ~14 days | 14–30 days |
| Orthopedic / cruciate ligament | 6 months | 14 days–12 months (often waivable) |
| Wellness add-on benefits | None or short | 0–30 days |
The clock starts on your policy's effective date — usually the day after you enroll and pay. Until each window closes, claims of that type simply aren't covered, no matter how clearly they'd qualify otherwise.
Why Waiting Periods Exist
Waiting periods solve one problem: buying insurance on the way to the emergency room. Without them, an owner could notice a limp on Monday, enroll on Tuesday, and file a claim on Wednesday — turning insurance from risk-pooling into a discount scheme that would push premiums up for everyone.
Understood that way, the tiered structure makes sense:
- Accidents get the shortest waits because you can't fake or foresee a genuine accident, so fraud risk is low.
- Illnesses get ~14 days because many conditions brew visibly before diagnosis — the window filters out "enrolled after the vomiting started" cases.
- Cruciate and orthopedic issues get months because a partial ligament tear can smolder as an occasional limp long before the dramatic full tear, making it the classic condition people try to insure retroactively.
None of this is carrier-specific fine print; it's the industry's standard architecture, and it's the companion rule to the pre-existing condition exclusion covered in our pre-existing conditions guide.
The Real Trap: Symptoms During the Wait
Here's the detail that catches people. The waiting period doesn't just delay coverage — it converts anything symptomatic during the window into a pre-existing condition.
Example: you enroll on June 1 with a 14-day illness wait. On June 10, your dog starts scratching her ears. The vet diagnoses an ear infection on June 20 — after the wait ended. Covered? No. Symptoms began inside the window, so the condition predates coverage. Depending on the insurer and whether it's deemed curable, that could mean one excluded incident or a recurring exclusion.
Practical consequences:
- Don't schedule enrollment around a suspicious symptom. If something's already off, see the vet first — an excluded ear infection is cheaper than a policy shaped around hidden symptoms, and honesty protects future claims from denial.
- Enroll during boring times, not eventful ones. The best day to buy insurance is a day when nothing is wrong.
- Document health at the start. A vet visit shortly before or after enrollment creates a clean baseline record showing your dog was symptom-free — useful evidence if a claim reviewer later questions timing.
How to Shorten or Survive the Wait
You can't negotiate away waiting periods, but you have legitimate moves:
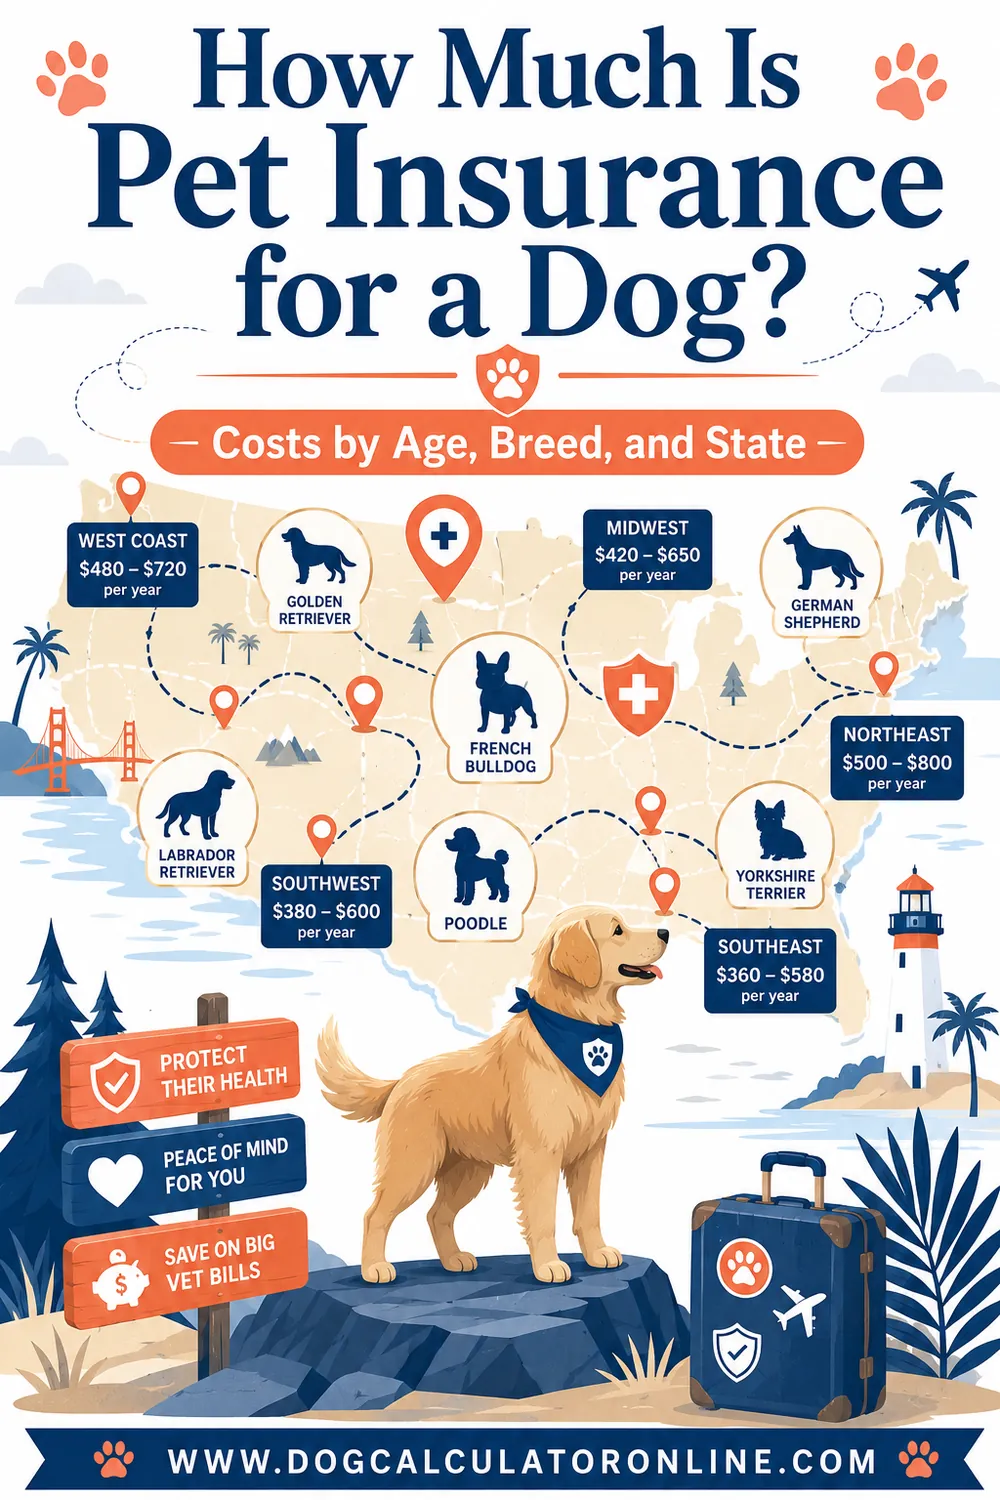
- Compare waits when comparing quotes. Accident waits range from 1 day to 15 days across insurers; illness waits from 14 to 30. If two plans price similarly, the shorter wait is free value. (Line them up alongside premiums using our guide to what dog insurance costs.)
- Ask about orthopedic waivers. Several insurers reduce the 6-month cruciate wait to 14–30 days if a vet examines your dog's knees within the first weeks of the policy and certifies them healthy. For large breeds, this single step can be worth thousands — cruciate surgery commonly runs $3,000–$6,000 per knee.
- Enroll before you need it — ideally at puppyhood. An 8-week-old puppy insured on day one clears every waiting period before adolescence, with nothing pre-existing. That head start is a big part of why insuring a puppy is the cleanest version of the product.
- Keep continuous coverage. Waits apply to new policies. Let a policy lapse and re-enroll later, and every clock restarts — plus anything that happened in the gap is now pre-existing. Renewal, by contrast, triggers no new waits.
- Bridge the gap deliberately. During your first weeks of coverage, treat yourself as self-insured: keep the emergency fund topped up and maybe delay high-risk activities (off-leash trail adventures, that dog-park introduction) until at least accident coverage is live.
Waiting Periods When You Switch Insurers
Switching companies means starting every waiting period over — and re-freezing your dog's health snapshot as the new pre-existing baseline. That's harmless for a young dog with an empty medical file and costly for a dog with any history.
If you do switch, avoid the classic mistake: don't cancel the old policy until the new one's waits have fully elapsed. Overlapping a month of double premiums is cheap compared to an uncovered emergency inside the new plan's window. The mechanics of claims across the transition follow the standard flow explained in how pet insurance works.
A Quick Timeline Example
Enroll a 1-year-old Lab mix on March 1 with typical terms (3-day accident wait, 14-day illness wait, 6-month orthopedic wait, waivable with exam):
| Date | What's covered |
|---|---|
| March 1 | Nothing yet — policy effective, clocks start |
| March 4 | Accidents covered (swallowed sock now claimable) |
| March 15 | Illnesses covered (ear infections, stomach bugs, and the serious stuff) |
| March 20 | Vet knee exam performed — orthopedic wait reduced per policy terms |
| ~April 3 | Orthopedic coverage live (instead of September 1) |
Thirty-odd days from enrollment to full coverage, versus six months on autopilot. The difference was one phone call and one exam fee.
Waits on upgrades and plan changes
One less obvious corner: waiting periods can also apply when you change an existing policy. Adding illness coverage to an accident-only plan triggers the illness wait for the new benefits; raising your annual limit or reimbursement rate mid-policy may subject the richer terms to a fresh window at some insurers; and adding a wellness rider usually starts its own short clock. Routine renewals with unchanged terms trigger nothing. The rule of thumb: new or expanded benefits get new waits, existing benefits never re-wait — so make plan-structure decisions early and adjust only the dials later.
Waiting Periods and Emergencies: The Worst-Case Question
"What if something happens on day 5?" is the question that makes people delay enrolling, which is backwards — delay only moves the exposed window later, it never shrinks it. If an emergency does land inside a waiting period: you pay the bill (payment plans and care credit lines exist for exactly this), the condition is excluded going forward, and the rest of the policy continues normally toward full coverage. Painful, but bounded — and statistically, a two-week exposed window is a far smaller risk than the months or years of exposure that come from postponing the decision to "sometime soon."
Your First 30 Days of Coverage: A Checklist
The waiting-period window rewards a little administration. Here's the sequence that extracts full value from a new policy:
- Day 0 — enrollment day. Save the policy documents PDF. Note three dates in your calendar: accident coverage start, illness coverage start, and orthopedic coverage start (or waiver deadline).
- Days 1–14 — the exposed window. Keep your emergency fund liquid; you're effectively self-insured. Skim the exclusions section of the actual policy — it's shorter than you fear and it's where every future dispute will be settled.
- Within the waiver window (often days 1–30) — the knee exam. If your insurer offers an orthopedic waiting-period waiver, book the vet exam now. It's the single highest-value errand in pet insurance, especially for breeds prone to cruciate injuries.
- Any time in month one — records housekeeping. Request copies of your dog's complete records from every clinic you've used. You'll need them at first claim anyway, and reading them yourself tells you exactly what an insurer will see.
- Set premiums to autopay. A lapsed policy restarts every waiting period and converts the interim into pre-existing territory — the most expensive administrative slip in this product.
Do these five things and the waiting period becomes what it should be: a brief formality at the start of years of coverage, rather than a trap discovered at claim time.
FAQ
What is the waiting period for pet insurance?
The gap between your policy's start date and when claims become payable: commonly around 14 days for accidents and illnesses (some insurers cover accidents within 1–3 days), and up to 6 months for orthopedic conditions like cruciate ligament tears.
Why does pet insurance have waiting periods?
To prevent people from buying coverage after a problem has already started. The waits filter out claims for conditions that were brewing before enrollment, which keeps premiums grounded in genuine future risk.
Can I get pet insurance with no waiting period?
Not for standard new policies in the US — every major insurer applies some wait. The realistic play is choosing an insurer with short accident waits and getting the orthopedic wait waived via an early vet exam where offered.
What happens if my dog gets sick during the waiting period?
The condition isn't covered, and because symptoms appeared before coverage began, it's treated as pre-existing going forward. Some insurers will cover curable conditions again after a symptom-free period; chronic ones stay excluded.
Does the waiting period restart at renewal?
No. Renewals continue coverage seamlessly with no new waits. Waiting periods only restart if you cancel and re-enroll, or switch to a different insurer.
How do I waive the 6-month cruciate waiting period?
Where offered, schedule an orthopedic exam with your vet within the insurer's specified window (often the first 14–30 days of the policy). If the vet certifies healthy knees, the insurer reduces the cruciate wait to the standard illness timeline. Confirm the exact procedure in your policy documents.
The Bottom Line
Waiting periods are short, standard, and survivable — but only if you respect the one rule that matters: coverage protects the future, never the past. Enroll on a boring day, get the knee exam if your insurer offers the waiver, and never let a policy lapse casually. The earlier in your dog's life you start the clocks, the less they cost you. Meanwhile, put the whole financial picture in one place with the free dog cost calculator — premiums, food, vet care, and all.