Pet Insurance Terms: A Plain-English Glossary
Pet insurance jargon boils down to about twenty terms, and once you know them, every policy page on the internet becomes readable. The big five — premium, deductible, reimbursement rate, annual limit, and pre-existing condition — control almost all of the money; the rest are supporting details that occasionally decide a claim. This glossary defines each one in a friendly sentence, then explains why it matters to your wallet, because a definition without stakes is just trivia. Once the vocabulary clicks, run your dog's real numbers through the free dog cost calculator to see where a premium would sit in your annual budget.
The Whole Glossary at a Glance
Here's the quick-reference version — every term in one table, sorted by how much money it controls. The sections below unpack each one with the detail that actually decides claims.
| Term | Plain-English meaning | Why it matters |
|---|---|---|
| Premium | Your monthly subscription price | The guaranteed cost; rises with age every year |
| Deductible | What you pay before coverage kicks in | Sets your out-of-pocket floor each year |
| Reimbursement rate | The % of the bill the insurer repays | Decides your share of every covered bill |
| Annual limit | The insurer's yearly payout cap | Your true ceiling in a catastrophe |
| Co-pay | Your % share after the deductible | The mirror image of the reimbursement rate |
| Pre-existing condition | Anything documented before coverage | Permanently or temporarily excluded |
| Curable vs incurable | Whether a pre-existing issue can requalify | Some past conditions can regain coverage |
| Bilateral condition | Two-sided conditions (knees, hips, eyes) | One side pre-coverage can exclude the other |
| Waiting period | The gap before coverage starts | Claims inside it are denied |
| Exclusion | Anything the policy refuses to cover | The list that defines your real coverage |
| Wellness rider | Optional routine-care add-on | Prepaid checkups, rarely a money-maker |
| Chronic-condition coverage | Ongoing illness covered across years | Decides whether lifelong issues stay covered |
| Accident-and-illness | The standard full policy type | What most people mean by "pet insurance" |
| Accident-only | Injuries covered, illness not | The budget option with a big gap |
| Claim | Your formal request for reimbursement | The paperwork that turns bills into checks |
| Direct pay | Insurer pays the vet, not you | Removes the pay-up-front cash crunch |
What Do the Money Terms Mean?
These five terms decide what you pay and what you get back. Master them and you can price any policy in your head.
Premium — the amount you pay every month to keep the policy active, typically $40–$70 for an adult dog's accident-and-illness plan. It matters because it's the one guaranteed cost in the whole arrangement: claims are maybes, premiums are certainties, and they rise at renewal as your dog ages.
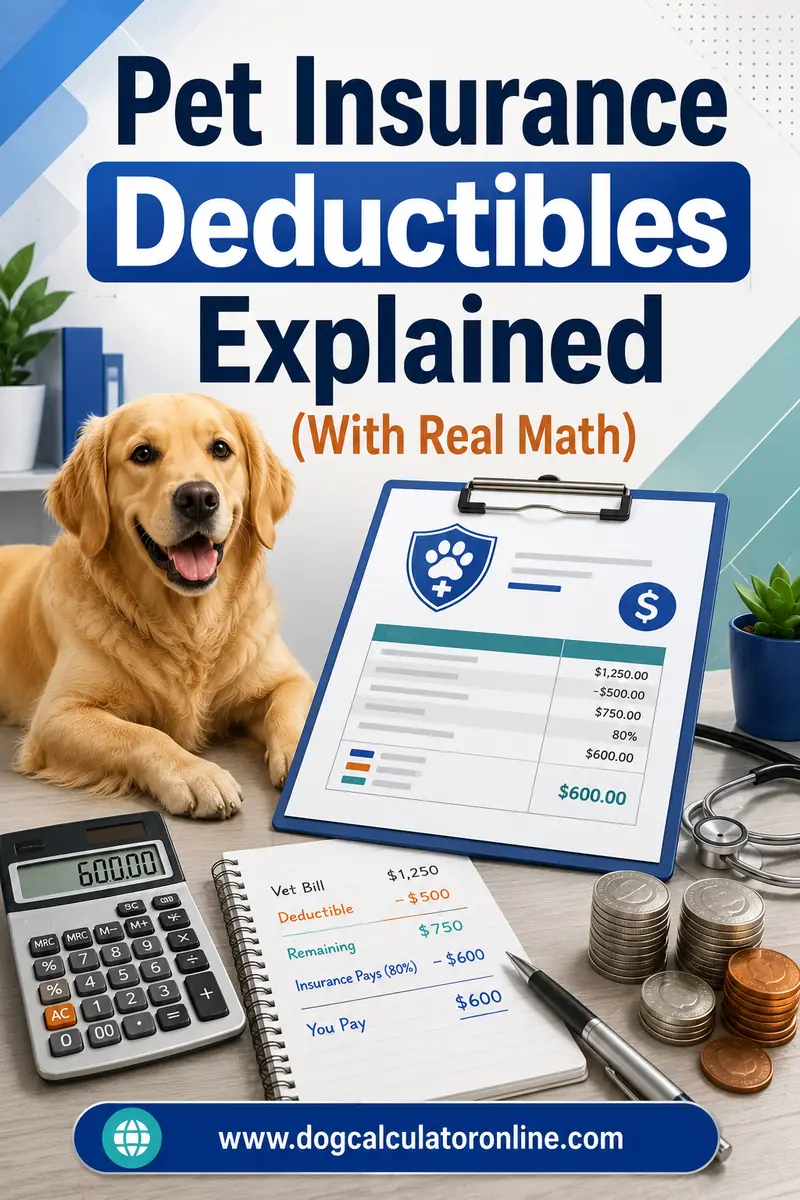
Deductible — the amount of vet bills you pay yourself before the insurer starts reimbursing, usually chosen from options like $250, $500, or $1,000. It matters because it's your main pricing lever: a higher deductible buys a lower premium, which is a sensible trade for people who want catastrophe protection rather than help with small bills. Most policies use an annual deductible (met once per policy year), but some use a per-incident deductible that resets with every new condition — the same $500 means very different things under those two designs, and our deductible explainer shows the math side by side.
Reimbursement rate — the percentage of the covered bill the insurer pays back after your deductible is met, usually 70%, 80%, or 90%. It matters because it applies to every single covered dollar: on a $5,000 surgery, the gap between 70% and 90% is $1,000 of your money. The reimbursement guide walks through full worked examples.
Co-pay (or co-insurance) — your share of the bill after the deductible, which is just the reimbursement rate flipped around: a 90% reimbursement rate means a 10% co-pay. It matters mostly as a reading skill — some policy documents describe the same plan from the insurer's side, some from yours, and knowing they're mirror images keeps you from double-counting.
Annual limit — the maximum the insurer will pay out in one policy year, commonly $5,000, $10,000, or unlimited. It matters because it's your real ceiling: with a $5,000 limit, a $14,000 emergency leaves you holding $9,000-plus no matter how good the rest of the plan looks. The annual limit explainer covers how to pick a number that actually protects you.
What Do the Medical-History Terms Mean?
This cluster decides what's coverable at all, and it's where most claim disputes live.
Pre-existing condition — any illness or injury that was diagnosed, treated, or showing symptoms before your coverage (and its waiting periods) took effect. It matters more than any other term in this glossary: insurers don't cover pre-existing conditions, they check your dog's full vet records at claim time, and even an undiagnosed symptom in the chart — a limp, a cough, "monitoring the left ear" — can anchor an exclusion. This is the engine behind all "enroll early" advice, and the pre-existing conditions guide covers the fine print.
Curable vs incurable pre-existing conditions — the distinction many insurers draw between past conditions that fully resolved (an ear infection, a stomach bug) and ones that are permanent (allergies, diabetes, arthritis). It matters because it's the merciful loophole: many policies will cover a curable condition again if the dog has been symptom-free for a stated window, often 6–12 months, while incurable conditions stay excluded for life. If your dog has any history, this clause is worth reading twice.
Bilateral condition — a condition that can occur on both sides of the body, like cruciate ligament tears, hip dysplasia, or cataracts. It matters because of a rule that ambushes people: if one knee tore before coverage, many policies exclude the other knee too, on the logic that the second tear was predictable. Cruciate injuries are among the most expensive common surgeries in dogs, so this single clause can carry four-figure consequences.
Hereditary and congenital conditions — problems a dog is born with or genetically prone to, like hip dysplasia in large breeds or breathing issues in flat-faced breeds. They matter because coverage varies: most modern accident-and-illness plans cover them if they weren't pre-existing, but some policies cap them or exclude them, and breed-prone owners should verify rather than assume.
What Do the Timing Terms Mean?
Waiting period — the stretch between enrolling and coverage actually starting: often a few days for accidents, around 14 days for illnesses, and up to 6 months for orthopedic conditions with some insurers. It matters because anything that happens inside the window is treated as pre-existing forever — and because orthopedic waits can sometimes be shortened with a vet exam, which is free money for large-breed owners. Details in the waiting period explainer.
Effective date — the day your coverage formally begins, from which all waiting periods are counted. It matters as the timestamp in every dispute: symptoms before it are pre-existing, symptoms after it (and after the waits) are coverable.
Policy year and renewal — the twelve-month cycle your deductible and annual limit live inside, and the moment the insurer re-prices your premium. Renewal matters because premiums rise with age and veterinary inflation every year; the smart response is re-tuning your deductible or reimbursement rate rather than canceling, since canceling converts your dog's accumulated history into pre-existing conditions on any future policy.
What Do the Coverage-Type Terms Mean?
Accident-and-illness plan — the standard full policy covering both injuries (hit by car, swallowed sock) and diseases (infections, cancer, diabetes). It matters because this is what people mean by "pet insurance" in almost every cost discussion, and it's where typical $40–$70/month pricing applies.
Accident-only plan — a cheaper policy covering injuries but no illnesses. It matters as the budget fallback: real protection against the swallowed toy and the broken leg, but nothing for the allergy, infection, or cancer claims that dominate lifetime vet spending. It's a reasonable bridge for a tight year, not an equivalent product.
Exclusion — anything the policy explicitly won't cover, listed in the fine print: pre-existing conditions, breeding costs, cosmetic procedures, and often exam fees or food. Exclusions matter because coverage is defined by what's not on this list — reading it is the fastest way to understand a policy, and the what pet insurance does not cover guide tours the usual suspects.
Wellness rider (or wellness plan) — an optional add-on that reimburses routine, predictable care: vaccines, annual exams, dental cleanings, preventives. It matters because it's frequently misunderstood as extra insurance when it's really prepayment with a convenience fee; the math only works if you'd genuinely use every included service. Insurance is for the unpredictable — routine costs are usually better budgeted directly.
Chronic-condition coverage — the policy's promise to keep covering an ongoing illness (diabetes, arthritis, allergies) year after year once it's diagnosed during coverage. It matters enormously for lifetime value: a policy that covers chronic conditions continuously turns a diabetes diagnosis into a managed cost, while one that re-excludes conditions at renewal quietly abandons you exactly when insurance was supposed to pay off. Modern US policies generally cover chronic conditions for life, but confirm the wording before you buy.
How Do Claims and Payment Terms Work?
Claim — your formal request for reimbursement after paying a vet bill, usually filed through an app with the itemized invoice attached. It matters because pet insurance runs on a pay-first model: you settle with the vet, then the insurer pays you back, which means you still need enough cash or credit to front the bill.
Itemized invoice — the line-by-line version of your vet bill showing each service and its price. It matters because insurers require it to process claims, and asking the clinic for it before you leave beats chasing paperwork during a stressful week.
Direct pay (or vet direct pay) — an arrangement where the insurer pays the veterinary clinic directly, so you only cover your deductible and co-pay at checkout. It matters because it solves the biggest practical weakness of pet insurance — fronting a $6,000 bill while you wait for reimbursement — but it's not universal: it depends on the insurer offering it and the clinic accepting it, so ask both sides before an emergency, not during one.
Explanation of benefits (EOB) — the statement you receive after a claim showing what was covered, what was applied to your deductible, and what was reimbursed. It matters as your audit trail: EOB math errors happen, and the document is how you catch a bill that was processed under the wrong condition or rate.
How Do the Terms Combine on a Real Bill?
Vocabulary earns its keep when the invoice arrives, so here's the whole glossary working one $4,000 covered surgery, on a plan with a $500 annual deductible, 80% reimbursement, and a $10,000 annual limit — with the deductible not yet met:
- The waiting periods passed months ago and the condition isn't pre-existing, so the claim is valid.
- You pay the vet $4,000 and file a claim with the itemized invoice.
- The insurer subtracts your $500 deductible: $3,500 remains.
- It reimburses 80% of that — $2,800 — which fits comfortably under the annual limit.
- Your EOB confirms the math: the insurer paid $2,800, and your total cost was $1,200 (the deductible plus your 20% co-pay).
That's the entire machine. Every plan comparison you'll ever do is just these steps with different numbers plugged in — and any later flare-up of the same issue tests the chronic-condition coverage wording rather than starting from zero.
Frequently Asked Questions
What's the difference between a deductible and a co-pay?
The deductible is a fixed dollar amount you pay first, before the insurer contributes anything; the co-pay is the percentage share you keep paying on every bill after that. On an 80% reimbursement plan with a $500 deductible, you pay the first $500 plus 20% of everything beyond it.
What does "pre-existing condition" actually include?
More than formal diagnoses — it includes any condition that showed symptoms before coverage started, even if no vet ever named it. A limp noted in the chart before enrollment can exclude a later cruciate claim. This is why enrolling while the medical file is empty is the single highest-leverage move in pet insurance.
Is a wellness rider the same as pet insurance?
No. Insurance covers unpredictable accidents and illnesses; a wellness rider prepays predictable routine care like vaccines and checkups, usually with a fee built in. Many owners skip the rider and budget routine costs directly, keeping insurance for what can't be planned.
What is a bilateral condition exclusion?
It's a rule for two-sided conditions like knee ligaments and hips: if one side was injured before coverage, many policies exclude the other side too, treating it as predictable. Since second-side cruciate tears are common and expensive, this clause deserves a careful read for any dog with joint history.
What's the difference between curable and incurable pre-existing conditions?
Curable ones — like a resolved ear infection — can often regain coverage after a symptom-free window, commonly 6–12 months. Incurable ones — allergies, diabetes, arthritis — stay excluded permanently once they're pre-existing. The distinction is why a minor illness before enrollment isn't always a life sentence.
What does "annual limit" mean in practice?
It's the most the insurer will pay across all claims in one policy year; you cover everything beyond it. A $5,000 limit sounds large until one emergency surgery consumes it in a day, which is why catastrophe-minded buyers favor high or unlimited caps even at a slightly higher premium.
The Bottom Line
Twenty terms, one machine: the premium buys the promise, the deductible and co-pay set your share, the annual limit caps the insurer's, and the pre-existing rules decide what counts at all. Read any policy through that frame and the fine print stops being intimidating — it becomes a short list of numbers you can compare in minutes. When you're ready to see how a premium fits alongside food, vet care, and everything else your dog costs, the free dog cost calculator puts the whole annual picture on one screen.