How to File a Pet Insurance Claim
Filing a pet insurance claim follows one simple loop at almost every insurer: you pay the vet in full, submit the itemized invoice plus your dog's medical records through the insurer's app or portal, and receive reimbursement — typically 70–90% of eligible costs after your deductible — by direct deposit or check, usually within days to a few weeks. A minority of clinics also support direct pay, where the insurer pays the vet up front and you cover only your share. The process is genuinely easy once you've done it once; the failures almost always trace back to missing paperwork, not insurer trickery. And if you're still weighing whether a policy fits your budget at all, the free dog cost calculator shows where premiums sit among your dog's total yearly costs.
How Does the Reimbursement Model Actually Work?
Unlike human health insurance, most pet insurance runs on a reimbursement model: the insurer has no billing relationship with your vet at all. You can use any licensed veterinarian, emergency hospital, or specialist — there are no networks — because the transaction is between you and the insurer, after the fact.
That design has two practical consequences worth internalizing before your first claim:
- You need the cash (or credit) up front. A $2,500 emergency bill is yours at the counter, even if $1,800 of it is coming back. Owners who can't float that gap should ask about direct pay (covered below), a clinic payment plan, or keep a credit line earmarked for exactly this moment.
- The paperwork is the product. The insurer never saw your dog. Everything they know arrives through the invoice and medical records you submit, which is why documentation quality — not vet quality — decides how smoothly claims go.
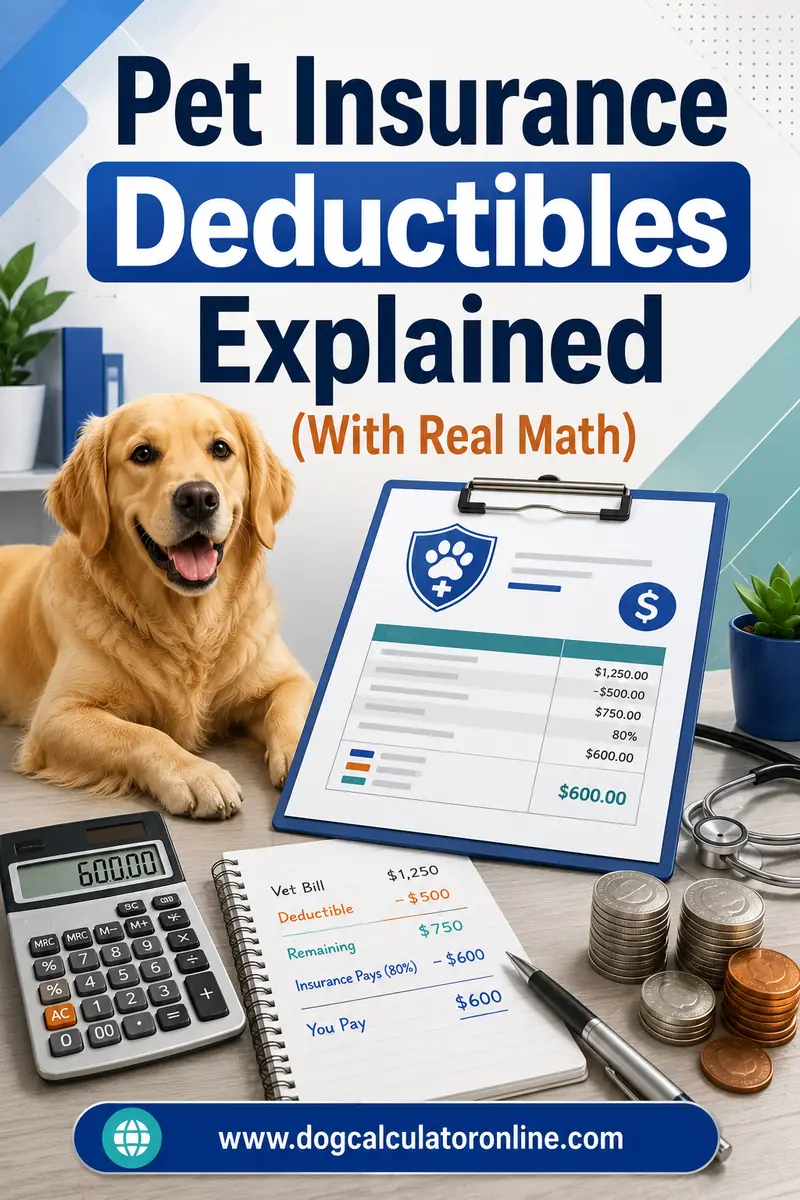
The percentage you get back and how the deductible bites are set by the plan you chose at enrollment. If those settings are fuzzy in your memory, the reimbursement explainer and deductible guide cover the math; the broader mechanics live in how pet insurance works.
What Do You Need Before You Submit?
Ninety percent of smooth claims come down to walking out of the clinic with the right two documents.
The itemized invoice. This is the line-by-line bill listing every service, medication, and test with its individual price — exam fee $65, radiographs $210, and so on. It is not the credit-card receipt showing a single total; insurers can't process a lump sum because they need to sort eligible items (the illness workup) from ineligible ones (the flea prevention you grabbed at checkout). Every clinic can print one — just ask at the desk.
The medical records for the visit. Also called the SOAP notes or chart notes — the vet's clinical write-up of what was found and done. For routine claims, the invoice often suffices; for a first claim, a large claim, or anything ambiguous, the insurer will want the notes. Many insurers fetch records directly from the clinic if you authorize it, which is the lowest-effort route.
Beyond those two, have on hand:
- Your policy number (the app fills this automatically)
- A short description of what happened — a sentence or two, in plain language
- Payment proof, occasionally requested for large bills
- For a first-ever claim: your dog's full prior medical history, because the insurer establishes a baseline of what existed before coverage — the process described in our pre-existing conditions guide
A habit worth stealing: photograph every vet invoice the moment it's handed to you, claim or no claim. A complete, dated paper trail is the single best insurance-friendliness move an owner can make, and it costs nothing.
How Do You Actually Submit the Claim?
Nearly every insurer now runs claims through a phone app or web portal, and the flow is remarkably consistent across the industry:
- Open the app and start a new claim. Choose the claim type — accident, illness, or wellness if you carry a routine-care rider (those route differently, as explained in wellness plans vs pet insurance).
- Answer the incident questions. When symptoms started, what happened, which clinic treated your dog. Be accurate about dates — this is the answer the insurer checks against the medical records, and mismatches cause delays.
- Upload the itemized invoice. A clear phone photo is fine. Include every page.
- Attach or authorize records. Upload the visit notes if you have them, or tick the box authorizing the insurer to request records from the clinic directly.
- Submit and note the claim number. You'll get status updates — received, in review, processed — and most apps show exactly which document is missing if the claim stalls.
Filing takes five minutes once you've done it before. Email and even fax submission still exist at some insurers for owners who prefer them, but the app route is faster and gives you a visible status trail.
Two timing rules matter. File promptly — policies set claim submission deadlines, commonly 90 days to a year after treatment, and a claim filed outside the window can be refused on timing alone. And file everything eligible, even small bills: many deductibles are annual, so a $150 claim that doesn't clear the deductible still chips away at it, making the next claim in the same policy year pay out sooner.
What Happens During Claim Review?
After submission, a claims processor checks three things, in roughly this order:
- Is the policy active and past its waiting periods? Treatment during a waiting period isn't eligible, no matter what it was for.
- Is the condition covered? They match the diagnosis on the records against the policy: accident and illness in, elective and routine out (the reason a spay claim goes nowhere on a standard policy), and — the big one — nothing pre-existing.
- Does the math check out? Eligible line items are totaled, the remaining deductible is subtracted, and your reimbursement percentage is applied, up to any per-incident or annual limit.
Typical timelines: simple, well-documented claims often process in 2–10 business days. First claims, large claims, and anything requiring records from multiple clinics can take 2–4 weeks, occasionally longer if a clinic is slow sending records. The number-one cause of delay across the industry is the insurer waiting on medical records — which is why authorizing direct record requests, or uploading the notes yourself, shortens the cycle more than anything else you control.
Reimbursement arrives by direct deposit (fastest — set it up before your first claim) or mailed check. The payment comes with an explanation of benefits: a line-by-line statement of what was eligible, what wasn't and why, what went to the deductible, and how the final number was computed. Read it — it's the document that teaches you how your specific policy behaves in practice.
What Is Direct Pay, and Can You Get It?
Direct pay (sometimes called vet direct billing) flips the model: the insurer pays the clinic its share up front, and you cover only your deductible and copay at checkout. For a $3,000 surgery on an 80% plan with the deductible already met, that's the difference between finding $3,000 today and finding $600.
The honest picture of availability:
- A minority of insurers offer it, and usually only at clinics that have joined their payment arrangement or through a pre-approval process for large planned procedures.
- The clinic must agree. Vet practices aren't obligated to bill insurers, and many prefer not to take on the administrative load. Emergency hospitals in urban areas are the most likely adopters.
- Pre-approval takes time. For scheduled procedures, direct pay typically requires submitting a treatment estimate for approval first — fine for a planned surgery next month, useless at 2 a.m.
If cash flow is the reason you want insurance, ask two questions before choosing a policy: does this insurer support direct pay, and will my regular clinic and nearest emergency hospital participate? If the answer is no — the common case — the fallback plan is a credit buffer or the clinic's own payment-plan options, arranged before the emergency rather than during it.
Why Do Claims Get Denied — and What Can You Do?
Most denials are predictable, and most of the predictable ones are preventable:
| Denial reason | What it means | Can you prevent it? |
|---|---|---|
| Pre-existing condition | Signs or diagnosis predate the policy | Enroll early, before chart notes accumulate |
| Waiting period | Treatment fell inside the initial exclusion window | Know your dates; don't file for that window |
| Excluded category | Routine, elective, cosmetic, or breeding-related care | Read the exclusions list once, properly |
| Missing documentation | Records or itemized invoice never arrived | Photograph invoices; authorize record requests |
| Lapsed policy | A missed payment paused coverage | Put premiums on autopay |
| Late filing | Submitted after the claim deadline | File within days, not months |
If a claim is denied and you think the insurer got it wrong, you have real options — denials are the start of a process, not the end of one:
- Read the explanation of benefits first. Identify the exact stated reason. A surprising number of "denials" are actually requests for missing documents wearing a scary label.
- Get your vet involved. For pre-existing disputes especially, a written statement from your vet clarifying that the current condition is unrelated to (or fully resolved from) an earlier note is the strongest evidence there is. A one-time ear infection at six months does not make every future ear problem pre-existing, and vets know how to say so in clinical language.
- File a formal appeal. Every insurer has an internal appeals process with its own deadline — commonly 30 to 180 days. Submit the vet statement and any additional records with a short, factual cover letter.
- Escalate if needed. Pet insurance is regulated as property-and-casualty insurance in the US; if an appeal fails and you believe the denial contradicts the policy language, your state insurance department accepts consumer complaints and insurers take those seriously.
Appeals succeed often enough — particularly on pre-existing and documentation disputes — that giving up on a four-figure claim without appealing is leaving money on the table.
How Do You Make Every Future Claim Easier?
A small amount of setup converts claims from a chore into a five-minute routine:
- Register the app and direct deposit on day one, not on claim day. Log in once so password recovery doesn't ambush you during a stressful week.
- Send your dog's full history at enrollment if the insurer offers a medical-history review. Some insurers will pre-assess what counts as pre-existing, so you know your coverage map before any claim is filed.
- Keep one folder — digital is fine — for everything dog-medical. Invoice photos, discharge sheets, lab results, vaccine certificates. Every document request becomes a thirty-second task.
- Tell the clinic you're insured. Front-desk staff process record requests constantly; clinics accustomed to your insurer respond to requests faster, and some will submit claims on your behalf.
- File small eligible claims anyway. They feed the annual deductible, and they establish a clean claims history with dates that protect you in later pre-existing discussions.
- Skim the explanation of benefits every time. Line-item errors happen — an eligible medication coded as routine, a math slip. Politely queried, they get corrected.
None of this is exotic; it's the same discipline as keeping receipts for taxes, applied to a dog. The owners who describe claims as painless are, almost universally, the ones with the folder.
Frequently Asked Questions
How long does a pet insurance claim take to process?
Simple, well-documented claims commonly pay out in 2–10 business days. First claims and large claims run longer — often 2–4 weeks — because the insurer reviews full medical records to establish what predates the policy. The biggest variable is how fast your clinic sends records, so authorizing direct record requests or uploading visit notes yourself is the best way to speed things up.
Do I have to pay the vet bill before insurance pays me?
Usually, yes. Most pet insurance is reimbursement-based: you settle the full bill at the clinic, then the insurer pays you back 70–90% of eligible costs after your deductible. The exception is direct pay, offered by a minority of insurers at participating clinics, where the insurer pays its share up front and you cover only your portion.
What documents do I need to file a pet insurance claim?
Two things carry almost every claim: the itemized invoice (each service and medication listed with its own price — not just a payment receipt) and the medical records for the visit. First claims usually also require your dog's complete prior history so the insurer can establish a pre-existing baseline. A clear phone photo of each document is acceptable at virtually all insurers.
Can the vet file the insurance claim for me?
Sometimes. Some clinics will submit claims on your behalf, and clinics familiar with your insurer respond quickly to record requests, which is where most delays live. Legally the policy is yours, though — you're responsible for accuracy and deadlines — so treat the vet's help as a convenience, and confirm through the app that the claim actually arrived.
Is there a deadline for filing a pet insurance claim?
Yes. Policies set claim-filing windows, commonly between 90 days and one year after the date of treatment, and claims submitted after the window can be refused on timing alone. The practical rule: file within days of the visit. Prompt filing also feeds your annual deductible sooner, which makes any later claim in the same policy year pay out faster.
What should I do if my pet insurance claim is denied?
Read the explanation of benefits to find the exact stated reason, then respond to that reason specifically. Missing-document denials just need the document; pre-existing disputes are best answered with a written statement from your vet showing the condition is new or unrelated. Every insurer runs a formal appeals process, and if that fails on a claim you believe the policy language supports, your state insurance department takes consumer complaints.
The Bottom Line
The claim loop is short: pay, photograph, submit, get reimbursed — with documentation doing all the heavy lifting. Set up the app and direct deposit before you need them, always leave the clinic with an itemized invoice, file fast, and treat a denial as a process rather than a verdict. Insurance handles the surprise bills; for the whole predictable rest of the budget — food, routine care, gear, and the premiums themselves — put real numbers on your own dog with the free dog cost calculator.