Does Pet Insurance Cover Spaying & Neutering?
No — standard accident-and-illness pet insurance almost never covers spaying or neutering, because insurers classify it as an elective, planned procedure rather than an unexpected accident or illness. The one common exception is a wellness add-on (a routine-care package some insurers sell alongside the main policy), which typically contributes a fixed allowance — often $100–$150 — toward the surgery rather than paying the whole bill. That gap matters, because a spay can cost anywhere from $50 at a subsidized clinic to $600+ at a private hospital. Before you decide how to pay for it, run your dog's full first-year numbers through the free dog cost calculator so the surgery sits in context instead of arriving as a surprise.
Why Doesn't Standard Pet Insurance Cover Spaying?
Pet insurance exists to protect you from costs you can't predict — the swallowed sock, the sudden limp, the diagnosis nobody saw coming. Spaying and neutering are the opposite of unpredictable: you choose the procedure, you schedule it weeks in advance, and you know the price before you walk in. Insurers call this category elective or preventive care, and standard accident-and-illness policies exclude it by design, the same way they exclude vaccines and routine dental cleanings.
There's a solid financial logic behind the exclusion, and understanding it helps the whole insurance picture click into place. Insurance works by pooling many owners' premiums to pay for the few large, random disasters that actually happen. If insurers also paid for procedures nearly every insured puppy gets, they'd simply have to raise everyone's premiums by roughly the cost of the procedure — plus administrative overhead. You'd end up prepaying your own spay through the premium, with a middleman fee attached.
So the exclusion isn't a loophole or fine-print trickery. It's the boundary line of what insurance is for. Our guide to what pet insurance covers draws that line in detail, but the short version is: unexpected = covered, planned = yours to budget.
What Counts as "Elective" to an Insurer?
The elective/preventive bucket is wider than many new owners expect. Alongside spay and neuter surgery, standard policies typically exclude:
- Vaccinations and boosters — core puppy series, rabies, annual updates
- Routine wellness exams — the yearly checkup where nothing is wrong
- Parasite prevention — flea, tick, and heartworm products
- Microchipping — a one-time, planned expense
- Routine dental cleanings — scheduled prophylactic cleanings under anesthesia
- Grooming and nail trims — never covered, anywhere
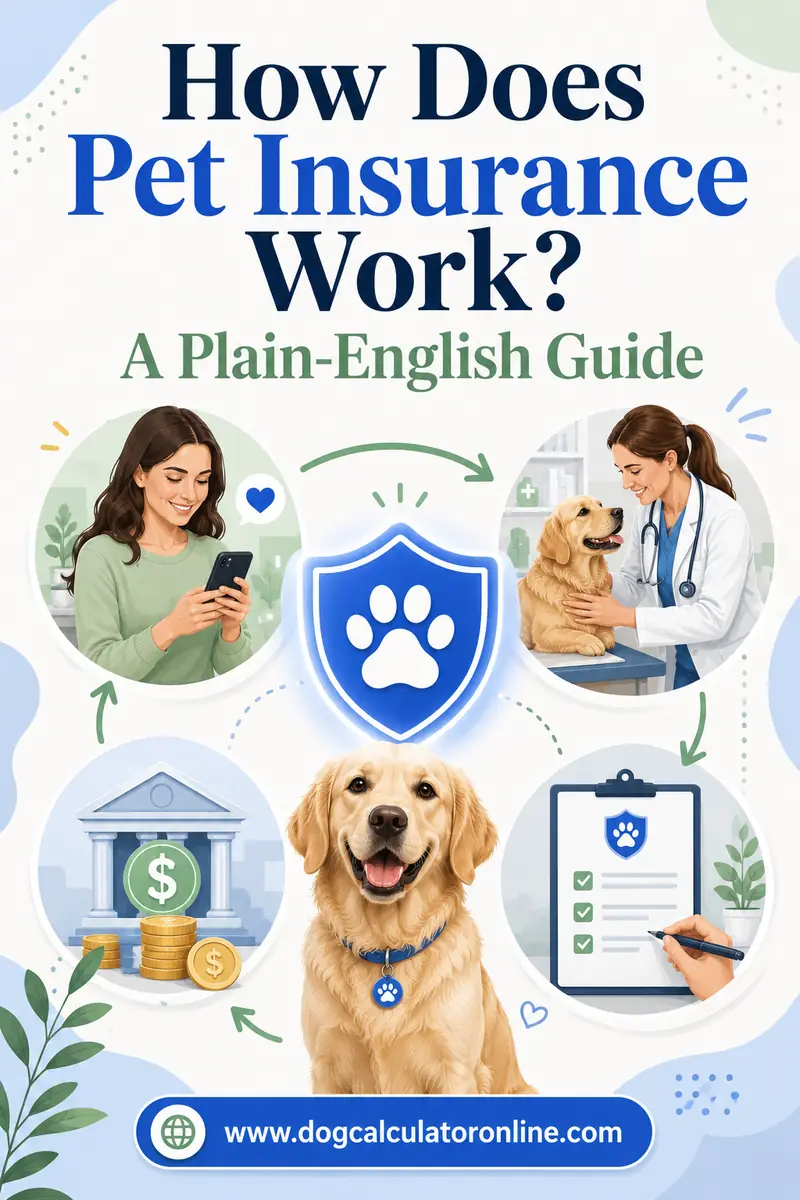
Notice the pattern: everything on that list is predictable in both timing and price. If you can put it on a calendar, insurance probably doesn't pay for it. If it shows up out of nowhere with a four-figure invoice, that's the territory insurance was built for — the mechanics of how those claims actually get reimbursed are laid out in how pet insurance works.
Can a Wellness Add-On Pay for Spaying or Neutering?
Sometimes, partially — and this is where the "usually not" answer earns its "usually."
Many insurers sell an optional wellness plan (also called a routine-care rider or preventive-care package) that bolts onto the main policy for an extra monthly fee, commonly $10–$30. Instead of reimbursing a percentage of surprise bills, a wellness add-on pays fixed dollar allowances toward scheduled care: so much for vaccines, so much for an annual exam, so much for flea prevention. Some — not all — include a line item for spay/neuter surgery, typically an allowance in the $100–$150 range.
Three things to understand before you count on that allowance:
- It's a contribution, not full coverage. If your spay costs $450 and the allowance is $150, you pay $300. The allowance is the same whether your clinic charges $80 or $600.
- Not every wellness package includes it. Some insurers only offer the spay/neuter benefit on their higher wellness tier. Read the benefit schedule — the actual dollar-by-dollar list — not the marketing summary.
- You're prepaying either way. Add up twelve months of wellness fees and compare it to the total allowances you'd realistically use. Often the numbers roughly cancel out, which means you're financing routine care through a subscription rather than saving money. The full breakdown of that trade-off lives in our wellness plans vs pet insurance comparison.
A wellness add-on can still make sense for people who prefer smooth, predictable monthly costs over lumpy bills — that's a legitimate budgeting preference. Just go in knowing it's a payment plan, not a discount.
How Much Does Spaying or Neutering Actually Cost?
Since you'll likely pay most or all of this yourself, the real numbers matter. Prices vary enormously by region, clinic type, and your dog's size and sex:
| Where you go | Typical cost (spay) | Typical cost (neuter) |
|---|---|---|
| Nonprofit / subsidized clinic | $50–$150 | $40–$120 |
| Humane society or shelter program | $75–$200 | $50–$150 |
| Standard private vet clinic | $250–$500 | $150–$400 |
| High-cost metro private hospital | $400–$700+ | $300–$550+ |
A few honest notes on why the ranges are so wide:
- Spays cost more than neuters. A spay is abdominal surgery — more anesthesia time, more surgical time, more monitoring. A neuter is a shorter, less invasive procedure.
- Bigger dogs cost more. Anesthesia is dosed by weight, and surgery on a 90-pound dog takes longer than on a 9-pound one. Large and giant breeds routinely land at the top of each range.
- The quote may not be the whole bill. Pre-surgical bloodwork ($80–$200), pain medication to take home, an e-collar, and IV fluids are sometimes bundled and sometimes itemized. Ask what the quoted price includes before you book.
- In-heat or pregnant spays cost extra. Many clinics add $25–$100+ because the surgery is more complex. Timing the procedure with your vet avoids the surcharge.
Low-cost clinics are a genuinely good option, not a compromise on safety — most are staffed by licensed veterinarians doing high volumes of exactly this surgery. Organizations like the ASPCA maintain directories of low-cost spay/neuter programs, and many municipal shelters run voucher programs for residents.
Is the Timing of the Surgery an Insurance Issue?
Indirectly, yes — in one way people rarely think about.
Vets increasingly tailor spay/neuter timing to the individual dog. Small breeds are often done around six months; many vets now recommend waiting until 12–18 months for large and giant breeds, because the hormones involved in growth also affect joint development. That's a conversation to have with your own vet, not a decision to outsource to an article.
Here's the insurance angle: whatever timing you choose, the surgery creates vet-chart entries. If the pre-surgical exam or bloodwork turns up something new — a heart murmur, elevated liver values, a skin issue — and you haven't enrolled in insurance yet, that finding can become a pre-existing condition on any policy you buy afterward, which means it's excluded from coverage. Owners who plan to insure their dog generally come out ahead enrolling before the spay appointment, so that anything discovered during the workup is already inside the coverage window rather than outside it.
What If Something Goes Wrong After the Surgery?
This is the most useful nuance in the whole topic. While the planned surgery itself isn't covered, complications from it often are — because a complication is, by definition, unexpected.
Say your dog develops an incision-site infection, has an adverse reaction to anesthesia, or reopens the wound and needs emergency care. Many accident-and-illness policies treat those as new, unexpected medical events and reimburse them like any other claim, even though the triggering surgery was elective. Policies differ on this — a minority exclude complications of elective procedures — so it's worth checking the exact wording in your policy documents before surgery day.
If you do end up filing for a complication, the process is the standard one: pay the vet, gather the invoice and records, submit, and wait for reimbursement. We walk through every step, including the documentation that speeds things up, in how to file a pet insurance claim.
Two practical moves protect you here:
- Follow the discharge instructions literally. Insurers can deny complication claims if records show the aftercare plan was ignored — the cone stays on, the leash walks stay short.
- Keep every document. The surgical record, the discharge sheet, the itemized invoice. If a complication claim happens, you'll need the paper trail that shows what was done and when.
Should You Buy Insurance Just to Help With Spaying?
No — and this is worth saying plainly, because the math is unambiguous.
Suppose you add a wellness package at $20/month specifically because it includes a $150 spay allowance. Over a year you'll pay $240 in wellness fees to receive $150 back for the surgery, plus whatever other allowances you actually use. Unless you'd genuinely max out the vaccine, exam, and prevention allowances too, you're paying a premium for the privilege of prepaying your own bills.
The better frame: spay/neuter is a one-time, known, schedulable cost. The right tool for known costs is a budget line, not an insurance policy. The right reason to buy accident-and-illness insurance is the unknown costs — the $4,000 emergency that arrives with no warning. Buy (or skip) the main policy on those grounds, covered honestly in our first-year cost guides, and treat the surgery as part of the predictable spend alongside food, vaccines, and gear. Our annual dog cost guide shows where it fits among everything else year one throws at you.
If cash is tight in the surgery month, the cheaper paths are subsidized clinics, shelter voucher programs, and simply asking your vet about a payment plan — most practices would far rather arrange installments than see a surgery postponed indefinitely.
Does Spaying or Neutering Affect Your Insurance Itself?
A little — in three quiet ways that rarely make it into the brochures.
Some insurers price it in. Enrollment forms usually ask whether your dog is spayed or neutered, and some insurers quote slightly lower premiums for altered dogs. The actuarial reasoning is straightforward: altered dogs can't develop certain reproductive-organ conditions at all — pyometra (a life-threatening uterine infection in intact females) and testicular problems simply come off the risk list — and some insurers price that reduced exposure into the premium. The discount, where it exists, is modest; nobody should time a surgery around it.
Breeding-related costs are excluded either way. Standard policies exclude anything connected to breeding, pregnancy, and whelping. If you keep your dog intact with breeding in mind, know that the whole reproductive category — from pregnancy complications to cesarean delivery — falls outside a standard accident-and-illness policy.
The intact-dog conditions are covered until they aren't. Here's the timing trap worth understanding: pyometra in an intact female is generally a covered illness — often a $2,000–$5,000 emergency surgery. But if your dog develops it and you then decide to spay-and-treat, the insurer covers it as an emergency, while any later policy would call it pre-existing history. Insurance rewards deciding early, in both directions: enroll before problems appear, and make the spay/neuter decision with your vet on medical grounds rather than waiting for a crisis to make it for you.
None of this changes the headline answer — the elective surgery itself stays uncovered — but it's a good example of why reading the exclusions page once, calmly, before you ever need it pays off.
How Do Owners Actually Pay for Spay/Neuter?
A quick tour of the realistic options, from cheapest to most convenient:
- Subsidized/nonprofit clinics — often $50–$150 total. High-volume, experienced surgical teams. The waitlist can be a few weeks, so book early.
- Shelter and municipal voucher programs — many adoption contracts include a spay/neuter voucher, or the fee was already bundled into the adoption cost. Check your paperwork; plenty of adopters pay twice by accident.
- Your regular vet — the most expensive option but with maximum continuity: the surgeon knows your dog, and the records live in one place.
- Wellness add-on allowance — fine if you already wanted the wellness package for other reasons; poor as the sole justification.
- A dedicated pet savings buffer — even $25/month set aside from the day you bring the puppy home covers a private-clinic spay within a year.
Whichever route you choose, get the itemized quote in writing and confirm what's included. The difference between clinics is often less about surgical quality and more about what's bundled versus billed separately.
Frequently Asked Questions
Does any pet insurance cover spaying?
Standard accident-and-illness policies don't — spaying is classified as elective, planned surgery and is excluded across the industry. The only mainstream route to help is a wellness add-on, which some insurers offer with a fixed spay/neuter allowance, typically around $100–$150 toward the total bill.
Does pet insurance cover neutering a male dog?
No, for the same reason spaying isn't covered: neutering is a scheduled, elective procedure rather than an unexpected accident or illness. Wellness add-ons that include a spay allowance almost always apply the same allowance to neuters. The good news is that neuters generally cost less than spays — often $150–$400 at private clinics and under $150 at subsidized ones.
Are complications from spay surgery covered by insurance?
Often, yes. An incision infection, anesthesia reaction, or reopened wound is an unexpected medical event, and many accident-and-illness policies reimburse it like any other illness or injury claim even though the original surgery was elective. Some policies exclude complications of elective procedures, so check your specific policy wording before the surgery.
How much does it cost to spay a dog without insurance?
Anywhere from about $50 at a nonprofit or subsidized clinic to $700+ at a private hospital in a high-cost city. Size matters — large dogs need more anesthesia and longer surgery — and extras like pre-surgical bloodwork, pain medication, and an e-collar may be billed separately. Always ask what the quote includes.
Is a wellness plan worth it just for the spay benefit?
Almost never on its own. A typical wellness package costs $120–$360 per year and contributes perhaps $100–$150 toward the surgery, so the spay benefit alone doesn't pay for the plan. It only pencils out if you'd also fully use the vaccine, exam, and prevention allowances — in which case you're smoothing your cash flow rather than saving money.
Should I enroll in pet insurance before or after spaying my dog?
Before, if you plan to insure at all. Pre-surgical exams and bloodwork can surface new findings, and anything documented before enrollment becomes a pre-existing condition that future policies exclude. Enrolling first means anything discovered during the surgical workup falls inside your coverage rather than outside it.
The Bottom Line
Spaying and neutering sit firmly on the "planned and predictable" side of the line that defines pet insurance: the base policy won't pay, a wellness add-on may chip in $100–$150, and complications afterward are often covered because they're the one unpredictable part. Budget the surgery directly — subsidized clinics make it affordable almost everywhere — and save the insurance decision for what insurance is actually for. To see how the spay fits alongside food, vaccines, gear, and everything else in your dog's real budget, run the numbers with the free dog cost calculator.