Average Pet Insurance Cost for a Dog
The average cost of dog insurance in the US lands in the range of roughly $40–$70 per month for a typical accident-and-illness plan, with the industry-wide average sitting somewhere in the middle of that band — around $55–$65 per month, or about $650–$750 per year, according to recent annual reports from NAPHIA, the North American Pet Health Insurance Association. Accident-only plans are far cheaper, usually $15–$30 per month, because they skip illness coverage entirely. Your own quote can sit well outside those ranges, though, because averages blend every breed, age, ZIP code, and plan setting into one number. This guide unpacks what the averages really mean and which levers move your price — and if you want to see how a premium fits into your dog's total yearly budget, the free dog cost calculator puts every line side by side.
What Does Dog Insurance Cost on Average?
Start with the most credible number available. NAPHIA — the North American Pet Health Insurance Association, the industry group whose member companies write the large majority of US pet policies — publishes a yearly State of the Industry report with actual average premiums, calculated from real policies in force. In recent years, its reported average for dog accident-and-illness coverage has worked out to roughly $650–$750 per year, or about $55–$65 per month, with accident-only dog coverage averaging in the neighborhood of $200–$250 per year.
Those figures are worth anchoring on because they're derived from millions of real policies rather than marketing quotes. But two honest caveats apply. First, the exact averages shift a little every year — premiums have generally trended upward alongside veterinary prices, so treat any single figure as a snapshot, not a constant. Second, an average is not a quote. The blended number includes tiny senior Chihuahuas in rural counties and young Great Danes in Manhattan, and those two dogs do not pay anything like the same premium.
For practical planning, the more useful frame is a band: most US dog owners buying a standard accident-and-illness plan land somewhere between $25 and $100 per month, with the fat middle of that distribution around $40–$70. If your quotes are coming back inside that band, you're seeing normal pricing. Our monthly cost guide slices these same numbers by dog size and plan type if you want the month-to-month view.
Why Is "Average" a Slippery Number?
Averages compress a wide, lumpy distribution into a single point, and with pet insurance the distribution is very wide. It's entirely normal for one dog to be quoted $28 per month and another $115 for the same insurer and the same plan structure. Neither quote is wrong; they just sit at different spots on the same pricing model.
Three things stretch the distribution:
- The inputs multiply rather than add. An expensive breed in an expensive city at an older age doesn't add three small surcharges — each factor scales the others, which is how quotes end up at double or triple the average.
- Plan settings are chosen by the owner. Two identical dogs can carry very different premiums purely because one owner picked a $250 deductible with 90% reimbursement and unlimited payout, while the other chose $1,000, 70%, and a $5,000 cap.
- Averages lag the market. Industry averages describe policies already in force, including older ones. New quotes reflect current vet costs, which typically run higher.
So use the average the way you'd use a national average rent: a sanity check, not a prediction. The prediction comes from quoting your actual dog — and understanding the levers below tells you why the number comes back the way it does.
What Are the Big Levers That Set Your Premium?
Every insurer prices from the same basic risk factors. Here's the full set, roughly ordered by how much they can move your quote:
| Lever | Who controls it | Typical effect on premium |
|---|---|---|
| Dog's age | Time | Steady climb at renewal; steepens around age 7+ |
| Breed | Fixed at birth | Can swing quotes by 50–100% between low- and high-risk breeds |
| Location (ZIP) | Where you live | High vet-cost metros can run 30–50%+ above rural areas |
| Deductible | You | Higher deductible = lower premium, sometimes dramatically |
| Reimbursement % | You | 90% costs meaningfully more than 70% |
| Annual limit | You | Unlimited payout costs more than a $5,000 cap |
| Plan type | You | Accident-only costs a fraction of accident-and-illness |
Age: the lever nobody can hold still
Puppies quote lowest — often $30–$50 per month for solid accident-and-illness coverage — and premiums rise at every renewal as the dog ages, because older dogs file more and bigger claims. The climb is gentle through young adulthood and steepens from around age seven. This is also why the same coverage started late costs more from day one: insurers price your dog's age now, not the age they wish you'd enrolled at. The year-by-year picture is mapped out in our cost by age guide, and the timing implications in when should you get pet insurance.
Breed: hereditary risk, priced in
Insurers have decades of claims data by breed, and it shows in quotes. Breeds with well-known hereditary risks — flat-faced breeds with airway issues, giant breeds with joint and heart conditions, breeds prone to skin and allergy trouble — cost more to insure because they cost more to treat over a lifetime. Mixed-breed dogs typically quote below purebreds of similar size. You can't change this lever, but knowing it explains a lot of quote-to-quote variation between friends comparing notes.
Location: your vet market, mirrored
Premiums track local veterinary prices, because that's what claims get paid against. The same dog can be quoted very differently in a major coastal city versus a small Midwestern town — differences of a third or more are common. If you move, expect your renewal to reflect the new ZIP code.
The settings you actually control
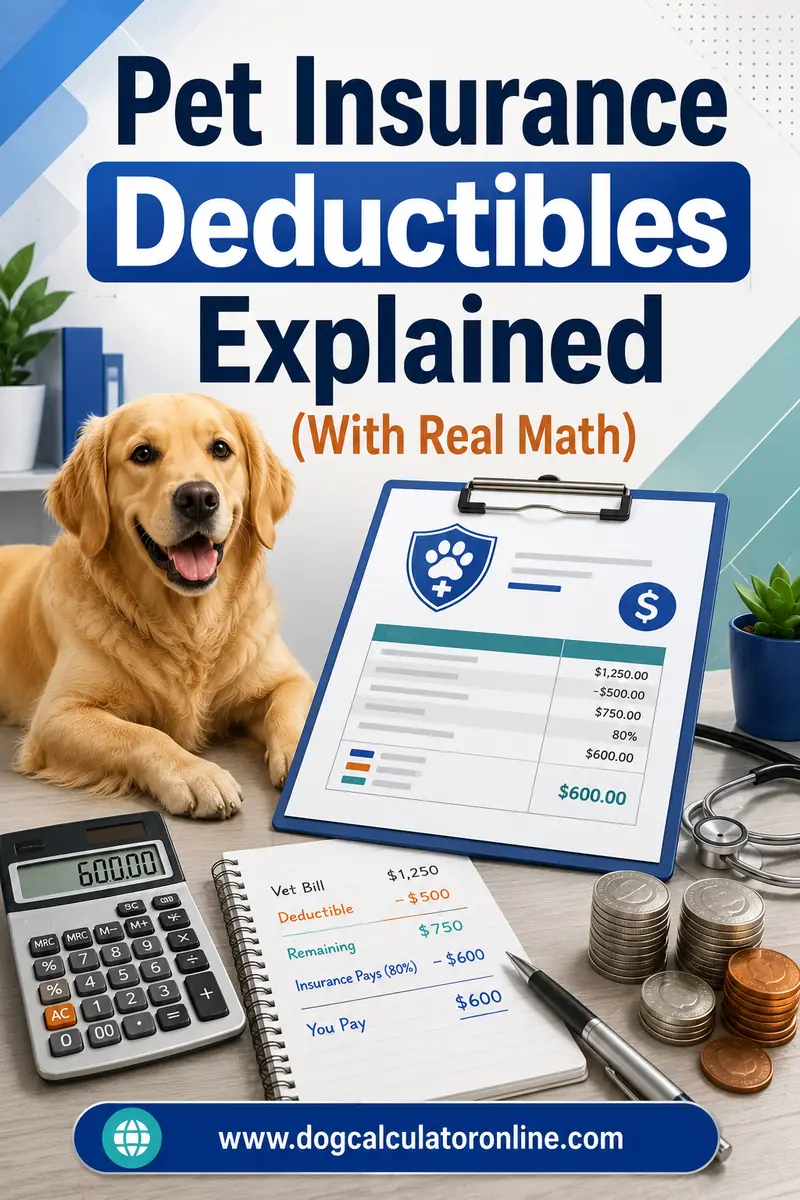
Deductible, reimbursement percentage, and annual limit are where you tune the price. Raising a deductible from $250 to $500 or $750 often cuts the premium noticeably; dropping reimbursement from 90% to 80% trims it further; capping the annual payout instead of going unlimited trims again. Stacked together, these choices can swing the same dog's premium by $20–$40 a month. The trade is real — you keep more of every future bill — so the goal is a configuration you could actually afford on a bad day, not the cheapest possible premium. Deductible mechanics get their own treatment in our deductible explainer, and the full factor list lives in what affects pet insurance premiums.
How Does Plan Type Change the Average?
"Dog insurance" covers three quite different products, and the average cost differs sharply between them:
| Plan type | What it covers | Typical monthly cost |
|---|---|---|
| Accident-only | Injuries, swallowed objects, toxin ingestion, wounds | $15–$30 |
| Accident-and-illness | Everything above plus sickness: infections, allergies, cancer, chronic disease | $40–$70 (wide range) |
| Wellness add-on | Routine care: vaccines, checkups, dental cleaning allowances | +$10–$30 on top |
Accident-and-illness is the default product and the one industry averages usually describe — illness claims, especially chronic conditions and cancer in mid-life and senior dogs, are where most lifetime claim dollars go. Accident-only is genuinely cheap and can suit tight budgets or owners of dogs whose illness coverage would be heavily excluded anyway, but understand what you're giving up: most of the expensive events in a dog's later life are illnesses, not accidents.
Wellness add-ons are a different animal entirely — they're not really insurance but pre-payment plans for predictable care. Since vaccines and annual exams happen on schedule, you're mostly routing known costs through an insurer, sometimes with a convenience markup. Run the math before adding one; budgeting those costs directly often comes out ahead.
What Would You Actually Pay at Each Life Stage?
Averages come alive when you map them across a dog's life. Here's an illustrative picture for a medium-sized, mixed-breed dog on a mid-tier accident-and-illness plan — treat the numbers as honest ballparks, not quotes:
- Puppy (under 1 year): roughly $30–$50 per month. The cheapest coverage of the dog's life, and the age when enrolling locks in a clean medical record. First-year specifics are in our puppy insurance cost guide.
- Young adult (1–4 years): roughly $35–$60. Premiums drift upward gently at renewal; claims at this age skew toward accidents and acute issues.
- Middle age (5–7 years): roughly $45–$75. Chronic conditions start emerging in predisposed dogs, and pricing begins reflecting it.
- Senior (8+ years): roughly $70–$120+. The steep part of the curve. Owners who enrolled young keep coverage for whatever developed along the way; new enrollments at this age face both these prices and exclusions for anything already on file.
Two things stand out in that arc. First, the lifetime spend is substantial — a dog insured from puppyhood to age thirteen might see $8,000–$15,000 in total premiums, which is exactly why the decision deserves real thought rather than autopilot. Second, the premium you pay later is shaped by choices made early: enrollment age sets where you start on the curve, and continuous coverage determines whether mid-life diagnoses are covered or excluded.
How Can You Lower the Cost Without Gutting Coverage?
There's a right way and a wrong way to chase a smaller premium. The right way keeps catastrophe protection intact:
- Raise the deductible first. This is the cleanest trade — you absorb more of the routine-sized claims in exchange for a meaningfully lower premium, while the policy still catches the $6,000 disaster.
- Keep reimbursement at 80% or above if you can. Dropping to 70% saves modestly but bites hardest on exactly the giant bills you're insuring against.
- Consider a capped annual limit rather than unlimited. A $10,000 annual cap covers the vast majority of bad years at a lower price than unlimited; just don't cap so low that one surgery blows through it.
- Skip the wellness add-on unless the arithmetic clearly favors it. Predictable costs rarely benefit from an insurance wrapper.
- Ask about discounts. Multi-pet discounts of 5–10% are common, and some employers offer group rates.
- Don't churn policies to chase intro pricing. Switching insurers resets waiting periods and converts everything in the chart since your original enrollment into pre-existing conditions with the new company. The teaser savings are rarely worth it.
The wrong way is buying a plan so hollowed out — tiny limit, low reimbursement, huge deductible — that a genuine emergency still wrecks your finances. At that point the premium buys mostly paperwork.
How Does the Premium Fit Into the Total Cost of a Dog?
Insurance is one line in a bigger budget, and it's worth seeing in proportion. A typical US dog costs somewhere in the range of $1,500–$4,000 per year across food, routine vet care, preventives, grooming, gear, and boarding — before any insurance premium. At the industry-average premium, insurance adds roughly $650–$750 to that, or around a fifth to a third of many dogs' annual budgets.
That framing cuts both ways. On one hand, the premium is real money — over a lifetime it can rival the cost of feeding the dog. On the other, it's the only line in the budget that caps your downside instead of adding to it: everything else on the list is a cost you'll definitely pay, while insurance converts an unpredictable five-figure risk into a fixed monthly number. Whether that conversion is worth it depends on your finances and temperament, but the decision goes better when you see all the numbers together — which is exactly what the free dog cost calculator is for.
Frequently Asked Questions
What is the average cost of dog insurance per month?
Around $55–$65 per month for accident-and-illness coverage, based on recent industry averages published by NAPHIA, with most owners landing somewhere in a wider $40–$70 band. Accident-only coverage averages far less, typically $15–$30 per month.
Why is my quote so much higher than the average?
Because averages blend every dog in the country, and your dog isn't average. An older dog, a breed with known hereditary risks, a high vet-cost ZIP code, or rich plan settings (low deductible, 90% reimbursement, unlimited payout) can each push a quote well above the blended number — and they compound.
Is cheaper accident-only coverage worth it?
It's genuinely useful protection against injuries, swallowed objects, and toxin ingestion at a low price. The gap is illness: infections, allergies, cancer, and chronic disease — which drive most veterinary spending in mid-life and senior dogs — aren't covered. It's a reasonable budget fallback, but know exactly what's excluded.
Does the average premium go up every year?
Generally yes, for two stacked reasons: your dog gets older, and veterinary costs rise across the market. Expect renewal increases through the dog's life, gentle in the early years and steeper from around age seven onward.
How much does dog insurance cost over a dog's whole life?
A dog insured from puppyhood through the senior years commonly accumulates $8,000–$15,000 in total premiums, depending on breed, location, and plan settings. That's why it pays to configure the plan deliberately — deductible and reimbursement choices compound over a decade-plus of renewals.
Is dog insurance cheaper if I start when my dog is a puppy?
Yes, in two ways. Puppy premiums are the lowest of the dog's life, and enrolling before anything appears in the medical chart means later conditions are covered rather than excluded. You can't freeze the price — it still rises with age — but you start at the bottom of the curve with the fewest exclusions.
The Bottom Line
The honest average for dog insurance is roughly $55–$65 a month for accident-and-illness coverage per industry data, inside a realistic $40–$70 band for most owners — but your number depends on age, breed, ZIP code, and the plan settings you pick, and it will rise as your dog ages. Use the average as a sanity check, quote your actual dog for the real answer, and tune the deductible rather than gutting the coverage if the price pinches. Then put the premium in context: run your dog's full yearly budget through the free dog cost calculator and decide with every number on the table.